A crash can leave you shaken and unsure what matters most. The next few hours may affect both your health and any claim you file later. What you say and the records you keep can protect both.
Secure the scene and call for help
First, stop your car and keep it stopped. Turn on your hazard lights so other traffic can see you. If your car still runs and is sitting in a live lane, ease it onto the shoulder where you can wait safely.
Check yourself for pain or bleeding. Then check your passengers and the people in the other car if you can reach them safely. Do not move an injured person unless there is an immediate danger and it is safe to act. Follow the emergency dispatcher’s instructions while help is on the way.
Call 911 when anyone may be injured, vehicles are creating a road hazard, or emergency help is otherwise needed. Report the collision as local law requires, even if the damage initially appears minor.
A prompt call may lead to police and medical records documenting the collision and any reported symptoms. Those records can reduce later uncertainty about when and how an injury occurred.
Stay where officers can find you. Don’t chase a driver who leaves.
If the other driver runs, try to remember the plate number and vehicle color. Write it down quickly before you forget. Look for cameras on nearby shops or homes. Those details may help with a hit-and-run claim if the at-fault driver cannot be found.
Keep breathing and keep conversation to a minimum. Shock can make people argue or say things they do not mean. You do not need to decide fault at the roadside.
State facts to the officer and avoid admitting fault
When officers arrive, give them clear facts. Tell them where you were heading and what you saw. Stick to what you know for certain.
Don’t guess about speed or distance. If you didn’t see the light, say so. Guesses can end up in the report and may be difficult to correct later.
Avoid saying sorry or stating that the crash was your fault. A polite apology can sound like an admission once it is written down. Let officers assess what the scene shows.
Ask how to obtain the police report. In Texas, the form is known as CR-3, while other states use different names or numbers, so ask the officer or clerk what to request. The report should list the drivers, insurers and road facts that adjusters will review closely.
Get the officer’s name and badge number. Write down the report number before you leave. You may need it when you call your insurer and follow up on medical care.
If officers ask whether you are hurt, be honest about what you feel. Don’t say you are fine simply to be polite. You can explain that you feel shaken and want to be checked.
Exchange the right information with the other driver
Exchange details with the other driver while you are still face to face. Don’t rely on your memory later. Phones can die and loose papers are easily lost.
Get the driver’s full legal name and phone number, along with their driver’s license number and home address. Take a photo of the license if the driver allows it.
Record the insurance and vehicle details. These include the insurer’s name, policy number, plate number and vehicle registration.
Claims can stall when a policy number or contact detail is wrong. Read the insurance card details back to the driver to confirm them. One incorrect digit can create avoidable delays.
Stay calm and avoid discussing fault. Don’t argue about who ran the light or braked too late. Exchange the necessary information and step back.
If there are passengers, get their names as well. If the driver says the car belongs to someone else, record the owner’s name from the registration. You want each relevant person connected to the vehicle.
You won’t be able to make this exchange after a hit-and-run. Focus on finding witnesses instead. Ask anyone who stopped what they saw and get their contact number.
Document the scene before it is cleared
Photos are more reliable than memory. Take more than you think you will need. Start with wide shots before moving closer.
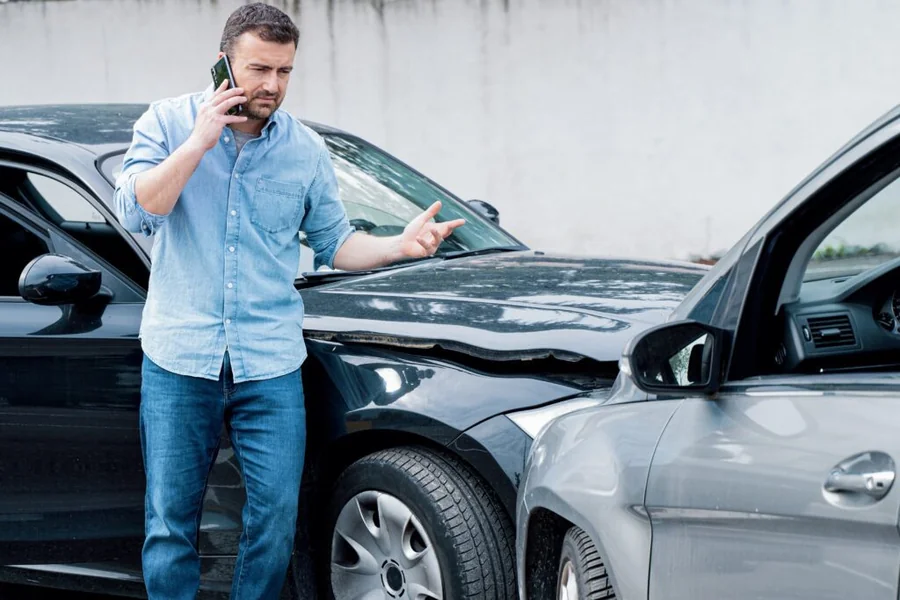
Photograph both cars from several angles. Capture the point of contact and each vehicle’s full lane position. Include the plates and the surrounding crash area.
Photograph the road itself, including skid marks and debris in the lane. Capture the traffic signs and signals controlling the intersection.
Light conditions matter. If it is dark or raining, note that on your phone. Weather and glare can help explain why a driver failed to stop in time.
Photograph the other driver’s license and insurance card. Do the same with the registration and plate. Keep those images in a separate folder so they are easy to find.
Speak to witnesses quickly because they often leave once traffic starts moving. Ask for a name, phone number and brief account of what they saw.
Independent witness statements may carry weight because those witnesses may have no financial stake in the claim. An adjuster may review them carefully when the drivers’ accounts conflict.
Don’t wait.
Tow yards can complicate the timeline too. If your car is towed, record the lot’s name and ask where the vehicle will be stored. Damage may change after cars are moved and stacked.
Notify your insurer without giving away your claim
Call your own insurer soon after leaving the scene. Most policies require prompt notice. Provide the date, location and names of the drivers involved.
Keep the conversation brief. Explain what happened in plain language. Avoid offering opinions about fault or the extent of your injuries.
You generally do not need to give the other driver’s insurer a recorded statement during an initial call. Your own policy may require reasonable cooperation, so review its terms or seek advice before declining your insurer’s request. Either way, avoid guessing or minimizing symptoms while you are still rattled.
The adjuster works for the insurance company and must evaluate the claim under the policy. A friendly tone does not mean the adjuster represents your interests.
Consider getting legal advice before signing a broad medical release or accepting a quick payment, especially if you do not yet understand your diagnosis. Depending on the release terms and applicable state law, accepting it could affect your right to seek further compensation if treatment continues.
This is the point when many people speak with a car accident attorney before answering detailed questions or signing forms. An injury lawyer can manage calls and correspondence while you focus on care, as well as explain options such as personal injury protection or uninsured motorist coverage if the other driver has insufficient insurance.
You don’t need to decide on a demand letter immediately. That formal settlement request usually comes after the records show the full extent of the loss. For now, avoid making statements that could understate that loss.
Seek timely medical care, even if symptoms seem mild
Adrenaline can mask pain. You may walk away from a hard impact and feel fine for several hours. Neck and back pain often becomes more noticeable the next day or the day after.
Seek prompt medical evaluation if you have pain, dizziness, confusion, weakness, or any other concerning symptom. Call 911 for a possible emergency. Tell the medical provider that you were involved in a car crash and describe your symptoms accurately, even if they initially seem minor.
Follow the treatment plan you receive. Attend follow-up appointments and complete therapy as directed. Fill prescriptions and keep the receipts.
Insurers look for a treatment gap, meaning the time between the crash and your first medical visit. A gap of several days can allow an adjuster to argue that you were injured elsewhere or were not badly hurt.
Don’t skip care because work is busy. Gaps can harm your health and weaken your credibility. If you cannot attend an appointment, reschedule promptly and keep a record.
Tell the doctor about earlier aches or injuries too. Previous back pain does not necessarily prevent a new claim, but hiding it can cause problems. Accurate records show what changed after the collision.
Keep a simple pain log. Record sleep loss, missed shifts and activities you can no longer manage comfortably, such as lifting your child or sitting through a drive. Those notes can help your doctor connect symptoms with changes in function.
In many states, personal injury protection can cover initial medical bills regardless of who caused the crash. In Texas, insurers must offer PIP, and a policyholder’s rejection must be in writing. Ask your insurer whether you carry it, and use health coverage if available rather than allowing bills to sit unpaid.
Protect fault evidence, damages records and filing deadlines
Fault rules vary by state, so check the law where the crash occurred. Texas follows proportionate responsibility. If you are found more than 50% at fault, you cannot recover damages, while a finding of 50% or less reduces payment by your assigned share.
This makes early evidence important. Skid-mark photographs, witness details and the police report can all help establish what happened. Without that evidence, fault may come down to one driver’s account against the other’s.
Hit-and-run cases follow a different route. When the driver cannot be found, your own uninsured motorist coverage may apply if you have it. Report the incident to police promptly and provide any partial plate number or vehicle description you recorded. Keep the report number with your claim documents.
Track financial losses from the first day. Economic loss covers costs that can be calculated. It begins with items such as hospital bills and pharmacy receipts.
It may also include lost wages and travel expenses for medical care. Save pay stubs, employer notes about missed work, towing slips and rental receipts. If future therapy appointments cause you to miss shifts, record those hours too.
Noneconomic loss covers the personal effects of the collision. It can include pain, lasting stiffness, sleep disruption and anxiety that continue after the immediate injuries begin to heal.
Don’t post about the crash online. Even an ordinary photo from a social event could be used to argue that you were not injured. Keep details of the case off social media until treatment is complete.
Store every record in one place, including the police report, discharge papers, imaging results and therapy notes. Add repair estimates and wage letters as you receive them. An injury lawyer or adjuster can only value losses that can be supported with evidence.
Watch the deadline. Texas generally allows two years from the crash date to file a personal injury lawsuit, while other states set their own limitation periods, which may be shorter or longer. Missing the applicable filing deadline can remove your right to sue even when the supporting evidence is strong.
Serious cases often require early attention because evidence can disappear quickly. Video may be recorded over, vehicles may be repaired or sold and witnesses’ memories can fade. Acting promptly helps preserve the claim while you recover.
You cannot control the other driver, but you can control your records, your words and your medical care. Keep them consistent to give a fair claim the strongest support possible.
